Credit Card Promos for Online Shopping in the Philippines (2026 Guide)
- Match the card type to where you actually spend: one marketplace, many sites, or big installment purchases.
- Bank promo codes and platform vouchers usually go in different fields, so they can often be stacked.
- A virtual card limits the damage if your card number leaks.
- Rewards, fees and promos change often. Check the bank's own page before applying.
- If a seller doesn't deliver, dispute in the app first, then ask your bank about a chargeback.
You fill the cart, get to checkout, and only then notice there was a bank promo you could have used. It happens to almost everyone who shops online. Finding more coupons isn't really the fix. What helps is having a card that fits how you shop, knowing where bank promo codes go at checkout, and keeping that card safe.
A warning first, since this is about money: card rewards, annual fees and promo terms change often and differ by bank. We won't quote rates here because they'd be wrong within months. Treat anything you read about a specific card, here or anywhere else, as a reason to check the bank's own page.
Does a separate card for online shopping make sense?
For a lot of people, yes. Some cards give extra points or cashback on online purchases, and cards tied to a marketplace may give more on that platform. Over a few big sales a year, that adds up.
The protection matters just as much. Credit card issuers have dispute and chargeback processes for purchases that were never delivered or that you didn't make. You won't get that from a direct bank transfer or e-wallet payment to a stranger. Then there are the bank promos themselves. Banks partner with Shopee, Lazada and others for cardholder-only codes, cashback and free shipping, and these are often announced only in the bank's app or social pages.
Which type of card fits you
There's no single best card. It's more useful to match the type of card to where your money actually goes.
| Card type | Suits | What to look at |
|---|---|---|
| Marketplace co-branded card (for example, a Shopee or Lazada partner card) | People who buy mostly on one platform | Rewards on that platform, included vouchers, annual fee |
| General online rewards card | People who split spending across Shopee, Lazada, Zalora and foreign sites | Bonus points on online and foreign spend, monthly caps, annual fee |
| Virtual or companion card | Anyone worried about card leaks | Separate number and limit, whether it earns rewards |
| Cashback card | Regular online spending like groceries and food delivery | Which merchants count, monthly cashback cap |
| Card with 0% installment deals | Big purchases like a laptop or appliance | Term, processing fee, minimum amount, eligible stores |

A co-branded card makes sense if most of your online spending already happens on one platform. The vouchers and extra rewards usually only work there, though. If you also buy from Zalora, iHerb or overseas stores, pair it with a card that rewards online spending generally.
A general online rewards card suits people who split a cart across several apps in the same sale, or who pay for streaming and software subscriptions online. Check whether subscriptions count as online spend and whether bonus points have a monthly cap.
A virtual card is a separate card number linked to your account, often with its own limit that you set. If it's the only card you use online and the number leaks, only that small limit is exposed, and you can cancel it without replacing your main card. Ask your bank whether it offers one and whether it earns rewards.
Stacking a bank promo with platform vouchers
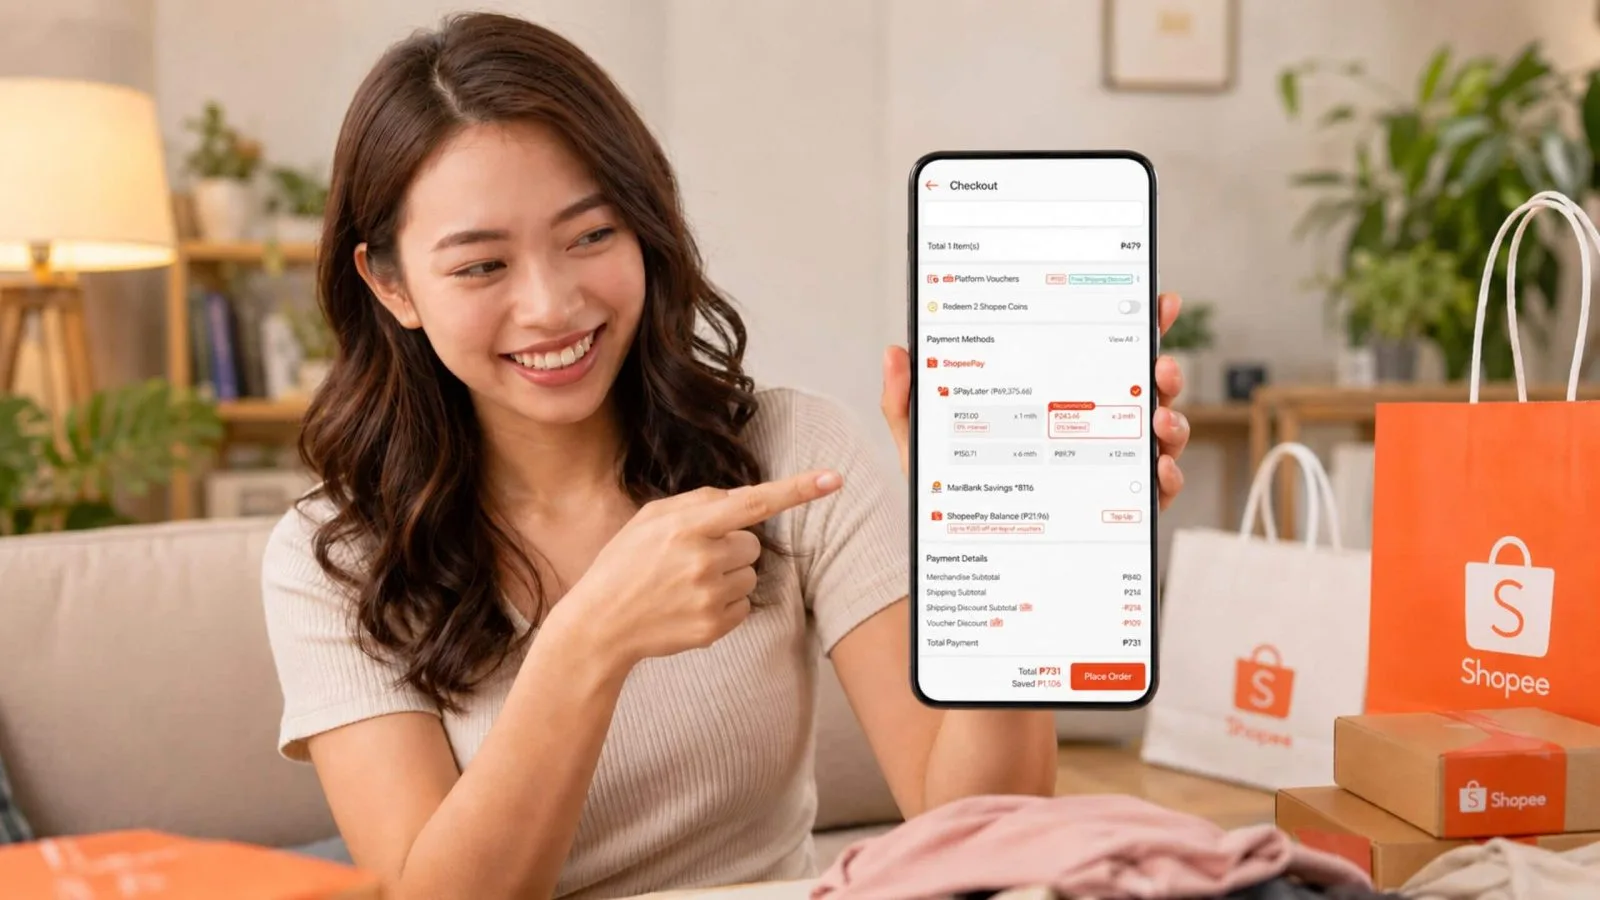
You usually don't have to choose between a card perk and a sale voucher. Platform vouchers and bank codes go in at different points in checkout, so they can often be used on the same order. Read the promo terms, though, because some bank codes say they can't be combined with other offers.
To see how it adds up, imagine a ₱1,500 cart (numbers made up for illustration): a ₱50 shipping voucher, a 10% shop voucher and a bank code would each take something off. How much you actually save depends on the minimum spend and the caps, so look at the final total before you pay.
The order that usually works:
- Add items to your cart before the sale starts. Vouchers run out, sometimes within hours.
- Claim the platform vouchers first: shipping, cashback and shop vouchers. Our Shopee voucher guide covers this step in detail.
- Check your bank's app or Facebook page the night before. Promo codes for big sales often come out around midnight with limited redemptions.
- Put platform vouchers in the voucher section and the bank code in the promo or payment-offer field.
- Choose the card the code is meant for. It usually only works with that card or card network.
- Screenshot the order summary before you pay.
For timing, see our sale calendar and 11.11 prep guide.
0% installment
For a laptop, a phone or an appliance, many banks offer 0% installment for a set number of months. Before you sign up, check the term, any processing fee, the minimum amount and which stores qualify. Zero interest doesn't help if you miss payments, so make sure the monthly amount fits comfortably.
Is a card the safest way to pay?
A credit card paid inside the app gives you two layers of protection, the platform and your bank. COD and e-wallets each have their own strengths. We compare them in COD, e-wallet or credit card: which is safest.
Keeping your card safe online
Use a virtual card for online shopping if your bank offers one. If it gets compromised, you cancel that one card, not your main account.
Don't let sites save your CVV. Saving the card number is convenient. Typing the three digits each time is a small price for keeping them off someone else's server.
Turn on transaction alerts and look at them. Report anything you don't recognize to your bank immediately, since the sooner you report, the easier the dispute.
And skip public Wi-Fi for checkout. Use mobile data or your home network. If you really have to use public Wi-Fi, make sure the address starts with https and don't enter card details if anything looks off.
Your rights if something goes wrong

Under the Consumer Act of the Philippines (RA 7394) and related e-commerce rules, online sellers have to describe products honestly, honor confirmed orders, and refund or replace defective items. Your card gives you an extra layer on top of that.
If a parcel never arrives or the item is wrong, start by documenting everything: order confirmation, payment receipt, chats with the seller and photos of what you got. File a return or dispute in the app while you're still within the buyer protection window. If the platform doesn't fix it and you paid by credit card, call your bank and ask about a chargeback. Banks have processes for disputing purchases that were never delivered or that you didn't authorize. If it's still unresolved, the DTI takes complaints at 1-384 and through its online Consumer Care portal, and the CICC handles fraud and phishing at 1326. Before any of that happens, our scams guide helps you avoid the bad sellers in the first place.
The people who save the most aren't chasing every sale. They have a card that fits where they spend, they know when bank codes come out, and they protect their card details. Turn on your bank's app notifications so you don't miss a midnight code, and hold on to receipts until your orders arrive.
General information, not financial advice. Card features, fees and promos change, so confirm the terms with the bank before you apply or pay.
Comments 0
Wala pang komento. Be the first to comment!
Leave a Comment